


A commercially viable fusion market will hinge on supply and demand, not on scientific breakthroughs alone.
Reaching that balance means building supply chains capable of delivering hardware at scale while lining up buyers willing to pay for power before the technology has proven it can run without subsidy.
Data centers, where the cost of energy is less of a barrier, are seen as fusion’s likely first paying customers.
“You need the supply chain to be able to build what needs to be built, and you need the demand there to enable the supply chain to work effectively,” said Adam Baker, head of fusion policy at the UK’s Department for Energy Security and Net Zero (DESNZ). “It’s just pure economics, but it’s far more complicated than that. Otherwise none of us would have jobs.”
“Harmonization is what’s needed, including supply chain, technology, finance and cooperation between public and private players,” said Kiyoshi Seko, president and chief operating officer of Kyoto Fusioneering. “Everything has to work together instead of competing with each other. That’s the stage the fusion industry is at, and we have to recognize that.”
Scott Hsu, fusion partner at Lowercarbon Capital, said he and colleagues at the U.S. Department of Energy (DOE) once calculated that fusion would need to hit $50 per megawatt hour (MWh) to compete in most power markets, in a paper published in 2021.
He said the goalposts have since moved. Energy costs are higher, and clean, firm electricity now carries a bigger premium.
“You need to get into a market first in order to have an opportunity to start going down the cost curve,” Hsu said. “The industry should be very attuned to what the market opportunities are, and also to geographical differences.”
“At the beginning it would be more rational to have a mixed industrial supply to data centers, for instance, where the cost of energy is not necessarily the first concern,” said Francesca Ferrazza, global head of magnetic fusion initiatives at Eni. “Different schemes could follow depending on the cost of energy in different places, and that should be chosen carefully.”
The view represents a rare point of alignment among developers, suppliers, financiers and regulators occupying very different positions in the fusion value chain.
Public demand as validation
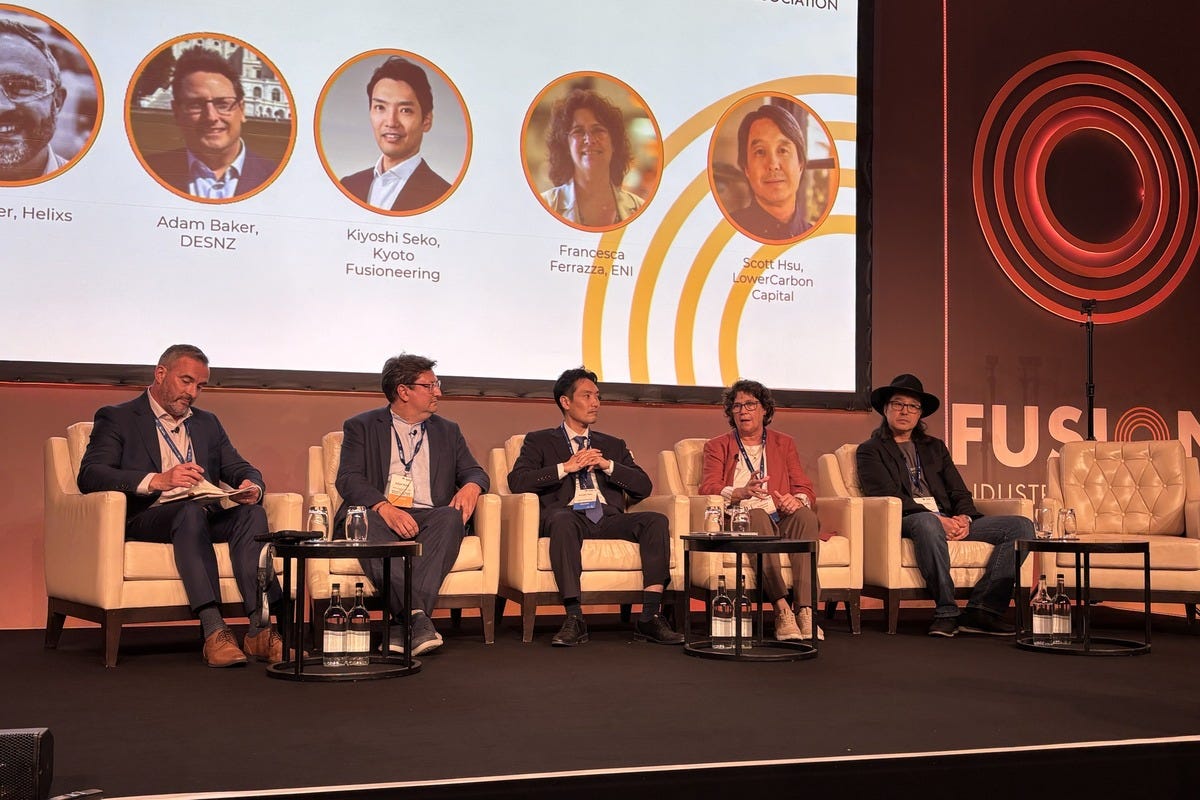
The comments came during a panel titled “Unlocking a Sector: Policies and Market Models Enabling Fusion” at the UK Fusion Forum 2026, hosted by the Fusion Industry Association in London on September 15.
The session was moderated by Steve Lawler, UK director of Helixos and chair of the Nuclear Industry Association’s Fusion Business Group.
The panel examined the policies, market structures and financing needed to attract private capital into commercial fusion projects. Lawler said unresolved questions remain around financing, insurance, supply chains, skills and testing facilities, even as the sector’s own message is that the UK is open for fusion business.
Hsu said the clearest example of public attention translating into political weight came in 2022, when scientists at the U.S. National Ignition Facility (NIF) achieved fusion ignition for the first time.
“Continued execution against truly significant de-risking milestones toward a fusion pilot plant is what’s going to move everything,” he said. “When NIF achieved ignition, nothing was more effective at getting worldwide attention on fusion. Suddenly people’s mothers and grandmothers were asking about it.”
“We don’t exist in a bubble. In democratic societies, it’s the public who sets the priorities,” Baker said. “What solves that isn’t big cross-party agreements, it’s public demand and public input. That’s what speaks to governments, not the promise of a long-term silver bullet, but jobs, regional investment and new skills.”
Kyoto Fusioneering announced a commitment of up to £130 million the day before the panel for what it calls Project Albion, a three-year effort to build breeder and blanket manufacturing capacity and a domestic supply chain in the UK for the UK Atomic Energy Authority (UKAEA)’s Spherical Tokamak for Energy Production (STEP) program.
“STEP needs breeder and blanket manufacturing capacity and a domestic supply chain, and someone has to build those capabilities, along with the workforce, here in the UK,” Seko said.
“There are still many missing technologies and missing infrastructure, and someone has to fill that gap to deliver fusion power at commercial scale,” he said. “That’s the contribution Kyoto Fusioneering is making, a commitment to the entire fusion industry.”
He said the company is still weighing whether to share supply chains globally or build them separately in each country where it operates, including the United States, Japan and the UK. He said the fusion market is not yet large enough to justify duplicating investment everywhere, so priorities have to be set.
Capital and government roles
“The investors’ greatest concern, what keeps us up at night, is if our companies run out of capital,” Hsu said. “That’s the existential problem. No matter how good the technology or how talented the staff, if they run out of money, it’s pretty much game over.”
He said the amount of non-dilutive funding, meaning grants and awards that do not dilute a startup’s equity, has to scale with each company’s stage, since capital needs vary widely across the sector.
“For a company like Commonwealth Fusion Systems (CFS), built on decades of published tokamak research, that validation matters less,” Hsu said. “For concepts that haven’t had as much public support, milestone validation from investor diligence is extremely valuable.”
He said the arrangements also signal to the wider market that policy and demand both exist, which helps attract customers.
Lawler opened the panel by citing a joint US-UK statement, signed the previous day, in which the two countries committed to harmonize fusion regulation. He also cited a DESNZ investment prospectus that values the global fusion market at between £3 trillion and £12 trillion.
“Regulation is an example of a role government has to take, because no one else will,” Baker said. “Our job is to create the environment in which the market can flourish.”
He said the sector still has to work out who bears the cost of decommissioning fusion plants at the end of their life, and whether companies have adequate access to capital.
He pointed to the National Wealth Fund, the British Business Bank and the government-seeded Starmaker One fund. He added that the biggest single thing that would move the dial in the UK is deeper utility involvement, not just in funding but in expertise and capability. Asked to picture the sector a decade from now, he had one image in mind.
Ferrazza said Eni’s experience varies sharply by region, shaped by differences in market understanding, technology maturity and regulatory openness across the US, the UK and Europe.
“We saw the future in the US investing in CFS,” she said. “We saw the dynamic and the potential, and it moved very fast and very well.”
Eni has also maintained a roughly 20-year relationship with the Massachusetts Institute of Technology (MIT), is listed on the U.S. stock exchange and has other long-running UK activities including carbon capture and storage (CCS) and offshore wind.
“In the UK we have a very solid relationship with UKAEA,” Ferrazza said. “The experience we built there with JET (Joint European Torus) is so solid that we fitted in very well. We’ve been in the country as a company for about 60 years.”
“For fusion, [Europe] was a very scientifically fragile community, and it’s now evolving into a more industrial approach,” she said. “It’s picking up, and I hope it picks up fast, because we need the Western fusion system working.”
She said continued investment depends on predictable regulation and sustained political support, and on raising public awareness.
With Project Albion underway and government funds like Starmaker One now live, the industry’s next test is whether that capital arrives fast enough to get first-of-a-kind fusion plants connected to the grid this decade.