


Britain is treating chip sovereignty as secure access through trusted partners, not making every semiconductor at home.
Rather than chase a giant domestic foundry, the government is backing high-value niches such as chip design and photonics, while relying on overseas fabs for the volume manufacturing the UK lacks.
"The first thing to say about sovereign capability is what it isn't, which is becoming self-sufficient. That's clearly not realistic," said Chris Bush, deputy director for semiconductors at the Department for Business, Innovation, Science and Trade (DBIST). “It’s hard for any country to be completely self-sufficient when it comes to the end-to-end semiconductor supply chain.”
He said sovereignty means building on what the UK does well, maintaining resilient access to critical technologies and forming global partnerships that give Britain a role in key supply chains and access to facilities it does not have at home.
“It is about recognizing our strengths, doubling down on those, putting investment particularly into areas like skills and innovation,” he said. “It’s about making sure that we are able to support our existing companies like Arm, but also make sure that we’re growing that next generation of companies.”
His team led the government’s £1.1 billion AI Hardware Plan for artificial intelligence (AI) chips and systems, published earlier this year. A digital and technology sector plan names semiconductors among six frontier technologies and targets Britain’s first $1 trillion company.
Bush said he expects that company to emerge from semiconductors and AI hardware.
Asked by an audience member whether the UK plans a large-scale complementary metal-oxide-semiconductor (CMOS) foundry like those run by TSMC, he said no, adding that the position has held since the 2023 semiconductor strategy.
“We need to double down on our strengths. We have clear strengths in really high-value parts of the supply chain, so that’s where our focus is going to be,” he said.
Peter Stephens, director of government partnerships for the UK at Arm, backed that approach.
“As stewards of taxpayer funding, it’s important to recognize where you can get the biggest impact for the pound you spend,” he said. “Government’s role is to enable the innovation here to service that global ecosystem more broadly.”
He pointed to Britain’s strong ties with Taiwan and a new agreement between the UK Semiconductor Centre (UKSC) and Japanese foundry Rapidus. Bush added that the AI Hardware Plan includes a line on building a network of foundry relationships.
“The innovation that we see in the UK is likely to service a global ecosystem,” Stephens said. “The biggest challenge here is how do we make sure that these companies can engage their innovation with global ecosystems, and what role can government play to help remove those barriers?”
Prototyping before scale
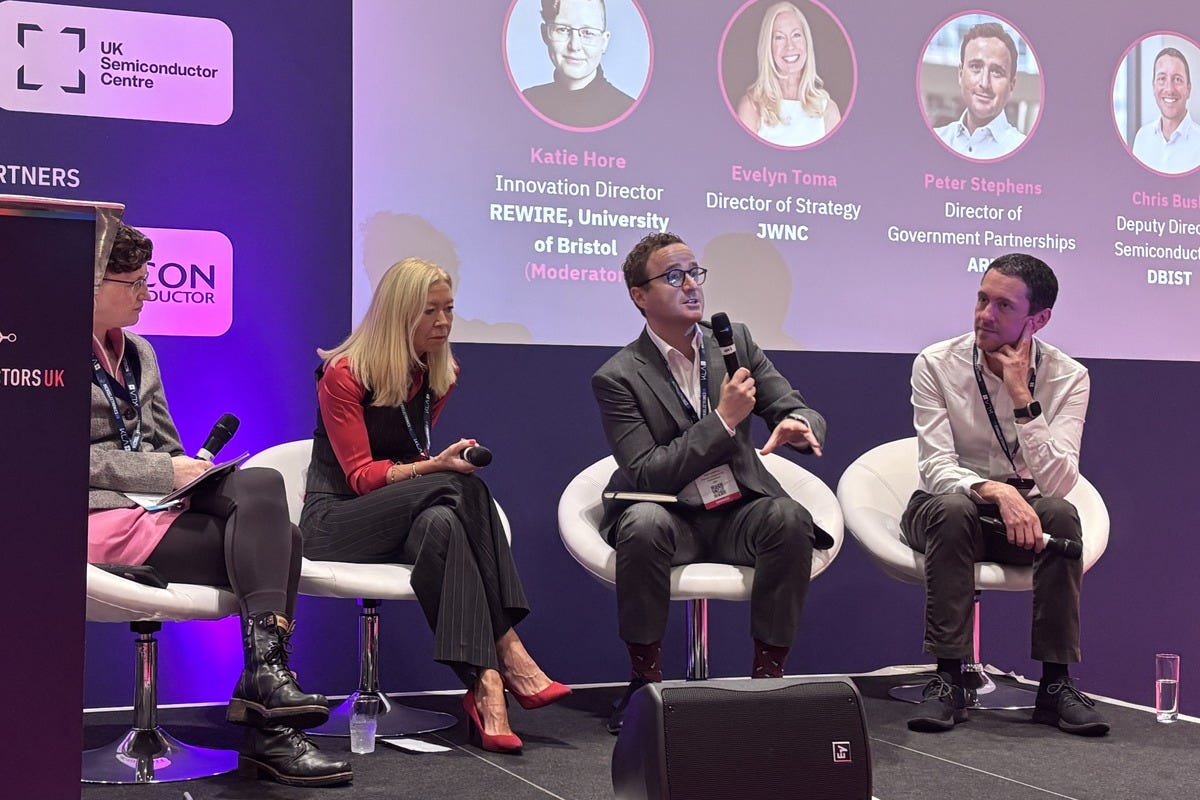
The panel, titled “Exploring Opportunities in the UK Semiconductor Industry,” was held at Microelectronics UK 2026 in London on September 29. Katie Hore, innovation director of REWIRE, the UK’s innovation and knowledge center for wide-bandgap power semiconductors at the University of Bristol, moderated the session.
Evelyn Toma is director of strategy at the James Watt Nanofabrication Centre (JWNC), a University of Glasgow wafer fab for photonics, quantum and novel semiconductors. She is also program director for a proposed second fab, the Critical Technologies Nanofabrication Facility.
She said companies tell her that working through European Union (EU) pilot lines is challenging. A device that misses its specification has to loop through design, fabrication, packaging and testing several times, which can add a couple of years of development.
“What do startups need very early? They need access to the infrastructure that allows them to prove their technology,” Toma said. “If they’re going to create IP (intellectual property), own it and capture the value, we need to make sure they’re making their market window.”
“We need thousands of devices to qualify products. Again, very challenging to get that from EU pilot lines,” she said. “There’s an argument for capturing some of the low-volume production in the UK that you either need for defense, or you can use to seed markets that will grow in the future.”
About 80% of JWNC’s work is in photonics. Its commercial arm, Kelvin Nanotechnology (KNT), brings in almost 40% of the center’s annual revenue and has worked with 150 companies in the past three years.
“An investment in infrastructure is not a one-off bet. It’s an investment in a whole community of people that need to use that infrastructure,” Toma said.
She cited Sivers Semiconductors, which employs 80 people at a wafer fab in central Scotland and has worked with the University of Glasgow for about two decades. When it won its first volume order, KNT handled part of the production.
“Between KNT and Sivers, over a couple of years, they supplied 3% to 5% of the global datacom market for lasers. That’s a really big number,” she said.
Sivers reinvested that revenue to bring the expertise in-house. In early September, it announced a $30 million expansion of its Glasgow indium phosphide (InP) fab to lift capacity above 100 million lasers a year, with the site due to be operational in the fourth quarter of 2027.
“I don’t see us ever being in real volume manufacturing in the UK. Maybe I’m wrong. I hope I’m wrong,” Toma said. “We could help companies do more of the scaling here onshore before they have to go offshore, which means that they own more of the IP and the value.”
She said Sivers is now pursuing a hybrid model, keeping research and development (R&D) and high-value production in Scotland while turning to Asian partners for high-volume, low-cost output.
Retirement cliff by 2040
Of all the constraints, skills may prove the hardest to fix.
“Skills investment does take 10 to 15 years to materialize. It’s 40% of the UK’s workforce in semiconductors that is expected to retire by 2040, which isn’t good,” Stephens said.
Bush said the government’s undergraduate bursary scheme, now run with TechFirst, has grown from 300 places last year to 400 this year and will reach 500 next year. Applications rose three- to four-fold in its second year.
“It’s not just giving a bursary to encourage those applications. It’s about having wraparound events and workshops, making sure that as those students go through their degree, they are interacting with semiconductor companies,” he said.
Applications to electrical and electronic engineering degrees rose 14% between 2024-25 and 2025-26, and the AI Hardware Plan raises stipends for semiconductor PhD students to keep them in Britain.
JWNC trains about 90 PhD students at a time but cannot yet train apprentices, which companies say they need.
Bush said the AI Hardware Plan defines the field more broadly than compute, and singled out photonic computing as an especially exciting area. The plan covers:
Compute
Photonics and data interconnects
Sensing
Power and energy systems
He cited London-based photonic chip startup Olix, which has raised $532 million across two funding rounds this year, and said infrastructure that lets such companies develop their products further in Britain is part of the answer.
“How else can we anchor these companies in the UK, given we’re always going to struggle to compete on capital with the likes of the US?” he said.
“Designing chips is something that the UK is very effective at. The investment on Station Road in Cambridge is now looking more and more like the Outer Ring Road in Bangalore or the main highways in Silicon Valley,” Stephens said.
Toma said established manufacturers need attention too. Companies have told her they were offered EU Chips Act money to invest in Spain instead, where imec (a semiconductor research and development hub) is building a pilot line in Málaga.
“One big investment into an already existing FDI (foreign direct investment)-owned company will be in the £30 million, £50 million and £100 million region. It takes so many startups to get to that sort of turnover that we do need to look after our established guys,” she said.
Bush said the UKSC, funded through the industrial strategy, gives overseas researchers, investors and businesses an easier entry point into the UK ecosystem.
“Sometimes there’s a sense that getting a collaboration is the end goal. That is not the end goal. The route to revenue and impact is the end goal,” he said.
With Sivers’ Glasgow expansion due online in late 2027 and bursary places rising to 500 next year, the test is whether Britain’s slower bets on skills and prototyping can keep pace with the partnerships it is building abroad.