


Europe’s push for chip sovereignty risks chasing the wrong goal: making every chip at home rather than owning the supply-chain choke points the world cannot do without.
The European Commission’s Chips Act 2.0 proposal, presented in June, frames the European Union (EU) as aiming to stay an indispensable player in the global value chain. Europe makes less than 10% of the world’s chips and remains exposed in critical segments.
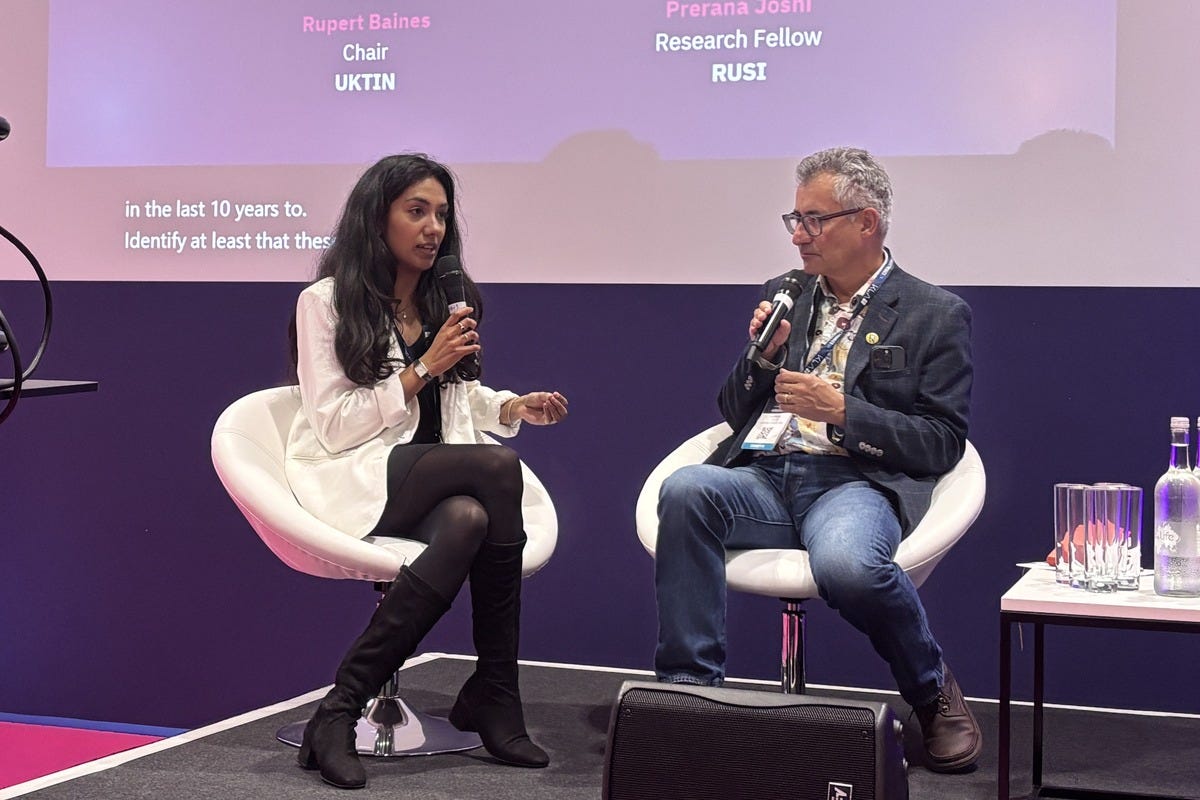
"There's a risk that the EU goes towards tech sovereignty being analogous to self-sufficiency, particularly when it comes to semiconductors and other types of advanced tech. In my perspective, indispensability is the direction that the EU should go in, and arguably the UK as well," said Prerana Joshi, research fellow in cyber and tech at the Royal United Services Institute (RUSI).
“It’s first of all identifying those strategic choke points or points of leverage in the supply chain and in the manufacturing of these things, and leveraging them fully,” Joshi said. “The EU Chips Act does have a pillar that pushes for this, but it’s voluntary; it’s information sharing between the member states, and ultimately, at what point does a member state want to protect its equities when it comes to identifying leverage and choke points?”
The UK’s £1.1 billion AI Hardware Plan, published in June, spreads support for artificial intelligence (AI) chips across innovation, skills, procurement and investment.
“The UK has done some good work on this, particularly in the AI Hardware Plan,” she said. “The distinction will be in the delivery of it, and in seeing if we can actually leverage those points, or if we are just identifying choke points of the now, but not necessarily for the future.”
Rupert Baines, chair of the UK Telecoms Innovation Network (UKTIN) Semiconductor Expert Working Group, pressed her on whether a degree of self-sufficiency is still realistic.
“We saw from COVID, when supply chains got disrupted, that the lack of availability of some commodity components closed down VW (Volkswagen) for weeks at a time,” he said.
“I’d separate the concept between self-sufficiency and mitigating critical vulnerabilities,” Joshi said. “There’s a risk that we equate sovereignty with ultimately owning, manufacturing and doing everything onshore, but it’s really that distinction of control and leverage.”
She said onshoring chips for consumer electronics is impractical, since Europe does not own that part of the supply chain. Baines agreed.
Execution lags the strategy
The discussion took place at Semiconductors UK, part of the Microelectronics UK 2026 conference organized by IQPC Exhibitions in London on September 29. The session, titled “The EU CHIPS Act 2.0 & Future Policy,” examined how geopolitics shapes sovereignty and chip supply chains.
Baines, who hosted the conversation, has spent about 30 years in semiconductors, including as chief executive of UltraSoC, which Siemens bought in 2020. Joshi previously worked at two UK defense primes, BAE Systems Digital Intelligence and Ultra Intelligence and Communications.
“What is interesting is how we have six very different models around the world for government support. At one extreme, we’ve got China with huge amounts of government money going in and a very prescriptive, directed roadmap,” he said.
He placed the US and the EU in the middle, with money aimed at pump-priming the private sector, alongside Japan and its state-backed Rapidus foundry. Korea is vastly bigger but runs on private money, while the UK uses much smaller sums with laser-focused approaches. He doubted anyone has got it right.
“In terms of moving the needle, the EU is still struggling a little bit. The strategy made sense, the plan made sense, but the execution and the way the money is flowing doesn’t seem to be delivering what people had hoped for,” he said.
The first Chips Act helped mobilize more than €52 billion in public and private investment. The revision shifts its focus from building manufacturing capacity toward demand from strategic industries, but it does not set a dedicated budget.
Joshi asked whether the UK has bridged the gap between its industrial and security strategies.
“Short answer: no. I’m very impressed by the knowledge and the appetite to do things, but I don’t think we’ve joined up the dots yet. Some of the funding plans are very good and very smart,” he said.
“Things like ChipStart and the bursaries for students will improve things in the long term, but I don’t think there’s enough urgency,” Baines said. ChipStart is a government-funded incubator program run by Silicon Catalyst UK.
He chairs an expert working group that advised the Department for Science, Innovation and Technology (DSIT), now merged into the Department for Business, Innovation, Science and Trade (DBIST). The past decade brought two major crises, COVID and Russia’s war in Ukraine.
“I would like to think that governments and industry were preparing for a third one, and at this time would be better positioned. But unfortunately, I’m very worried that isn’t true,” he said. “With another shock like that, we’re going to be facing factories closed down again because we haven’t planned ahead.”
Stuck after Series A
Joshi asked how Europe could create another ASML, the Dutch maker of chipmaking machines. Baines said the problem is no longer starting companies but growing them.
“One of the starting points is building the startups, and across Europe in general we’re doing a very much better job of that. In the UK particularly, we’re probably several years ahead of most of continental Europe,” he said.
The Baltics have more startups per capita than anywhere, a ratio on a par with the Bay Area. Britain now has the academics, tech transfer officers, lawyers, venture capital (VC) funds and serial entrepreneurs needed for deep tech and semiconductor startups.
“That takes you from pre-seed to seed to maybe an A round, and that is when the wheels fall off,” Baines said. “It’s getting easier to do a startup, but it is still painfully difficult to get that company to grow, to become an Arm or an ASML that matters at scale.”
He said pension money could help close that gap.
“If we were speaking 10 years ago, I would have been very pessimistic. Semiconductors were out of fashion, VC didn’t like hardware, and the UK ecosystem was really hurting,” he said.
He said the Mansion House reforms and the Long-term Investment for Technology and Science (LIFTS) initiative are starting to take hold, with pension funds now taking big positions.
Under the Mansion House Accord, 17 large workplace pension providers have voluntarily pledged to put at least 10% of their default funds into private markets by 2030, with 5% going to the UK. Under LIFTS, the British Business Bank matched £ 250 million with £250 million from Phoenix Group.
Baines noted that Britain lacks prime contractors in many segments, with no bleeding-edge telecoms firm left like GEC or Plessey. Joshi, drawing on her time at two primes, pointed to a gap in commercial culture.
“We’re getting very good at the culture of startups and tech bros and VC hubs. From a diplomatic and economic leverage perspective, we’re good,” she said.
She said what has been missing is the ground in between, a culture of commerce and salesmanship that links technical procurement teams with their customers.
“Realistically, primes require some certainty of a purchase order at some point to be able to make an informed investment into their supply chains,” Joshi said.
She said trade delegations led by DBIST and UK Defence and Security Exports need to be multiplied and sped up.
Baines said he wants a clearer, funded roadmap that names which sectors are in scope and which are out, rather than initiatives and AI buzzwords.
Both speakers ended on optimism. He said hardware investment is swinging back, citing Pragmatic, Fractile, Olix and Cusp. Fractile raised $220 million in May, and Olix raised $312 million in August, the largest semiconductor funding round in European history.
With Chips Act 2.0 still before EU lawmakers and Baines’s roadmap yet to appear, the test is whether either side can turn choke-point lists into contracts.